Explore potential equipment leasing scenarios with our Plant & Equipment Lease Calculator. Test different lease amounts, residual (balloon) payments and repayment terms to estimate costs and see how varying finance assumptions may influence your business repayments and cash flow.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approval or eligibility decisions, or personalised recommendations. Actual repayments and costs may differ.
Business Asset Lease Details:
Important!
Business Asset Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Asset Lease Amortisation Calculator
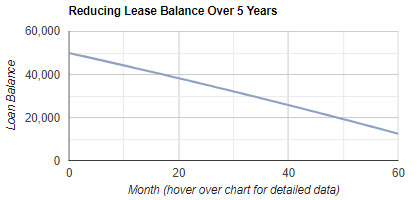
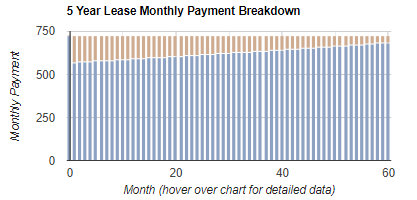
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Plant & Equipment Lease Calculator
Our Plant & Equipment Lease Calculator helps business owners estimate lease repayments before you speak with a lender. It’s important because changing the residual (balloon), term and interest rate can materially affect cash flow, total interest paid and the end-of-term payout amount. The calculator provides estimates only and is general information, not personal advice; consider your objectives, financial situation and needs, and check the lease contract, fees and tax treatment with your accountant or adviser.
How to complete the calculator (best-practice order):
1. Purchase Price: Enter the total amount you want to finance, using whole numbers only (no dots or commas). Include relevant on-road and acquisition costs you intend to finance, such as applicable tax, stamp duty, registration, insurance or other costs.
2. Balloon or Residual Value: Choose the residual as a percentage of the purchase price. A higher residual usually lowers the ongoing repayments, but increases the amount due at the end and can increase the overall cost across the term. Select a residual that matches your expected end-of-term plan (refinance, trade-in, or pay out).
3. Term of Loan: Select the number of years. Longer terms typically reduce repayments but can increase total interest paid. Use a term that aligns with the asset’s useful life and how long you expect to keep it.
4. Interest Rate: Select a rate to simulate. The displayed range is indicative only; your actual rate depends on the lender and your circumstances and can only be confirmed after you apply.
5. Calculate: Run the estimate, then re-run scenarios to compare different residuals, terms and rates for a clearer view of affordability versus total cost.
How to interpret the results:
1. Repayment estimate: Treat this as a guide for budgeting, not a quote.
2. Residual due: Note the end-of-term balloon amount you’ll need to pay or refinance.
3. Amortisation graphs: Review how the balance reduces over time and how each repayment splits between interest and principal, which helps you understand cost versus payoff progress.
Australian SME borrowing has taken a sharper turn upwards, with new September quarter reporting from Inside Small Business showing Banjo Loans recorded its strongest SME lending quarter since its barometer began in 2023. For business owners, the message is not simply that confidence has returned; it is that many firms appear to be treating finance as a buffer against still-uncertain trading conditions. - read more
Fresh attention around Australian Taxation Office interest charges is giving small and medium-sized businesses another reason to treat tax debt as a front-line cash flow issue rather than a back-office problem. From the current income year, deductions are no longer available for general interest charge and shortfall interest charge amounts incurred on unpaid or underpaid tax liabilities. In practical terms, that can lift the after-tax cost of carrying ATO debt. - read more
Fresh small business tax reporting has put asset write-offs back in the spotlight, with many Australian SMEs again weighing whether to bring forward spending on vehicles, machinery, technology or fit-out. The practical message is clear: tax incentives can improve the after-tax cost of an eligible purchase, but they should not be treated as a substitute for a disciplined finance decision. - read more
Fresh industry reporting on business lending suggests Australian SMEs are still looking for ways to invest in productive assets, even while broader trading conditions remain uneven. Demand for finance linked to vehicles, machinery, technology and other equipment appears to be holding attention because these purchases can directly improve capacity, efficiency or service delivery. - read more
Personal guarantees, collateral and PPSR registrations can create important obligations for business borrowers, company directors and sole traders. This guide explains what these terms commonly mean in Australian business lending and what to check before signing. - read more
When it comes to financing your business, selecting the right option is crucial to its success. The right financial tools can help your business grow, manage expenses, and navigate unforeseen challenges more effectively. - read more
Sustainable business funding helps Australian SMEs explore finance for projects that reduce environmental impact or support socially responsible operations. Understanding the available options, eligibility criteria and application process can help business owners plan green initiatives with greater clarity. - read more
Running a small or medium-sized business in Australia can be an exciting venture, full of potential and growth opportunities. However, maintaining a healthy cash flow is critical to keeping that dream afloat and thriving. This is where working capital loans come into play. - read more
Knowledgebase
Refinancing: The process of obtaining a new mortgage to replace an existing one, often to secure a lower interest rate.