Business Loans :: News
SHARE

Share this news item!

Government Extends SME Lending Exemption to Support Small Businesses

10-Year Extension Aims to Ease Access to Finance Amid Rising Fuel Costs

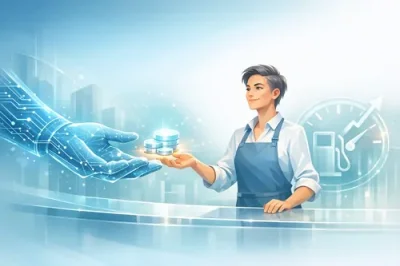
Government Extends SME Lending Exemption to Support Small Businesses?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

The Australian government has announced a significant extension of the Small Business Responsible Lending Obligation (RLO) exemption, prolonging it by an additional 10 years.
This decision comes as part of a broader support package aimed at assisting small and medium-sized enterprises (SMEs) grappling with the ongoing fuel crisis.

Initially introduced during the COVID-19 pandemic, the RLO exemption was designed to stimulate lending within the SME sector. It allows eligible businesses—those with fewer than 100 employees or annual revenues of $5 million or less—to access loans without undergoing the standard responsible lending assessments, provided the funds are used for genuine business purposes. The exemption was originally set to expire in October 2026.

In light of the current economic challenges, particularly the escalating fuel prices impacting operational costs, the government has opted to extend this exemption until 2036. Treasurer Jim Chalmers emphasized that this move is intended to improve access to finance for small businesses while reducing regulatory burdens. "We will help small businesses access easier and faster credit by extending the Small Business Responsible Lending Obligation exemption for a further 10 years," Chalmers stated.

For SMEs, this extension offers a crucial lifeline, enabling quicker and more straightforward access to necessary funding. By bypassing some of the more stringent lending criteria, businesses can secure the capital needed to navigate the current economic landscape, invest in growth opportunities, and manage cash flow more effectively.

However, it's essential for business owners to approach this opportunity with caution. While the relaxed lending requirements can expedite access to funds, it's important to ensure that any borrowed capital is used judiciously and aligns with the company's long-term financial strategy. Overleveraging or mismanagement of funds could lead to financial difficulties down the line.

In conclusion, the government's decision to extend the RLO exemption reflects a commitment to supporting the SME sector during challenging times. By facilitating easier access to finance, this measure aims to bolster the resilience and growth potential of small businesses across Australia.

Published:Saturday, 11th Apr 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

ATO interest changes sharpen the cost of tax debt
15 Sep 2026: Paige Estritori
Fresh attention around Australian Taxation Office interest charges is giving small and medium-sized businesses another reason to treat tax debt as a front-line cash flow issue rather than a back-office problem. From the current income year, deductions are no longer available for general interest charge and shortfall interest charge amounts incurred on unpaid or underpaid tax liabilities. In practical terms, that can lift the after-tax cost of carrying ATO debt. - read more
Why tax incentives should not rush your next business loan
08 Sep 2026: Paige Estritori
Fresh small business tax reporting has put asset write-offs back in the spotlight, with many Australian SMEs again weighing whether to bring forward spending on vehicles, machinery, technology or fit-out. The practical message is clear: tax incentives can improve the after-tax cost of an eligible purchase, but they should not be treated as a substitute for a disciplined finance decision. - read more
What stronger equipment finance interest means for SME borrowers
01 Sep 2026: Paige Estritori
Fresh industry reporting on business lending suggests Australian SMEs are still looking for ways to invest in productive assets, even while broader trading conditions remain uneven. Demand for finance linked to vehicles, machinery, technology and other equipment appears to be holding attention because these purchases can directly improve capacity, efficiency or service delivery. - read more
What rising business risk means for SME loan applications
25 Aug 2026: Paige Estritori
Fresh business risk reporting is sending another reminder that Australian SMEs are operating in a more selective lending environment. Measures such as payment defaults, external administrations and weaker trading conditions are being watched closely across the market, particularly in sectors exposed to discretionary spending, construction delays and cost inflation. - read more


Business Loan Articles

Sustainable Business Funding: How Australian SMEs Can Finance Green Initiatives
Sustainable business funding helps Australian SMEs explore finance for projects that reduce environmental impact or support socially responsible operations. Understanding the available options, eligibility criteria and application process can help business owners plan green initiatives with greater clarity. - read more
How Do Lenders Assess a Business Loan Application in Australia?
Applying for a business loan involves more than completing an application form. Lenders typically assess a range of factors when deciding whether to approve a loan, including the financial position of the business, its ability to repay the loan and the information provided as part of the application. - read more
Secured vs Unsecured Business Loans: What's the Difference?
Secured and unsecured business loans are two common types of finance available to Australian businesses. While both provide access to funding, they differ in how they are structured, the security requirements, borrowing limits and other loan features. - read more
Loan or Line of Credit? What’s Best for Your Business?
When it comes to financing your business, selecting the right option is crucial to its success. The right financial tools can help your business grow, manage expenses, and navigate unforeseen challenges more effectively. - read more

Knowledgebase
Annual Percentage Rate (APR):
The annual rate charged for borrowing or earned through an investment, expressed as a percentage.